DFW Hail Damage Roof Repair Guide for Homeowners (2026)
When a severe hailstorm sweeps through the Dallas–Fort Worth metroplex, homeowners are often left with hidden structural liabilities beneath their shingles. In North Texas, severe weather events frequently generate wind-driven hail ranging from marble-sized ice pellets to golf-ball-sized hail strikes. Knowing how to assess storm impacts, document physical damage, navigate state-specific insurance regulations, and partner with local roofing contractors can mean the difference between a smooth restoration and costly out-of-pocket delays.
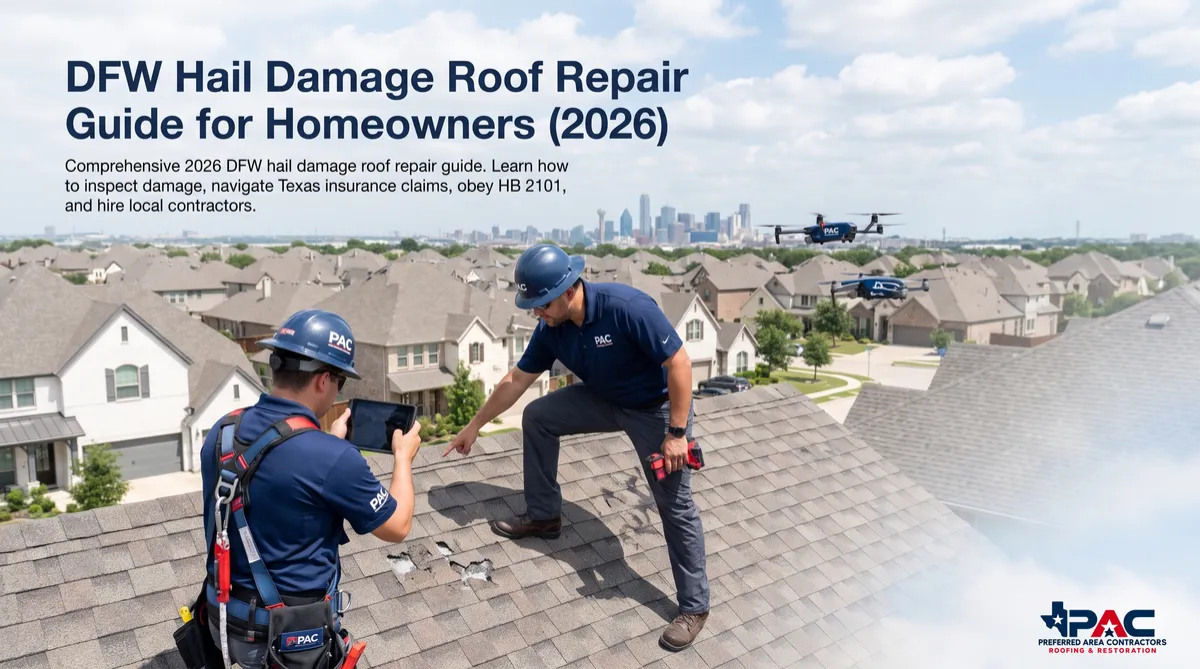
DFW Hail Damage Roof Repair Guide for Homeowners — A structured, multi-step process for evaluating North Texas storm damage, completing ground-level inspections, filing accurate Texas insurance claims under state law (including HB 2101), and selecting local contractors for roof repair or replacement.
Key related topics covered here include Commercial Roofing, Roof Leak Repair, Roof Inspections, especially DFW Hail Damage Roof Repair Guide for Homeowners, with practical context for decision-makers.
Key Takeaways for DFW Homeowners After a Hailstorm
caption>Essential Steps and Regulatory Requirements for DFW Roof RestorationKey Takeaways for DFW Homeowners After a Hailstorm| Strategy | Why It Matters |
|---|---|
| Perform Ground-Level Documentation | Captures immediate date-stamped photographic proof of damage to soft metals, gutters, and downspouts before emergency cleanups occur. |
| Schedule an Independent Inspection | Uncovers micro-fractures and underlying matting tears prior to meeting with the carrier adjuster, preventing missed scope items. |
| Verify Texas Deductible Compliance | Ensures full compliance with Texas state law (HB 2101 / HB 2102) prohibiting deductible absorption, protecting homeowners from claim fraud. |
| Distinguish ACV vs. RCV Payouts | Clarifies net out-of-pocket costs and recoverable depreciation timelines before signing material contracts. |
1. Why DFW Hailstorms Cause Severe and Often Hidden Damage to Asphalt Shingle Roofs
Structured, FAQ-rich content on DFW Hail Damage Roof Repair Guide for Homeowners often improves scanability and retrieval clarity—especially when sections answer specific questions in plain language.
The Dallas–Fort Worth metroplex sits firmly inside the southern boundary of "Hail Alley." According to meteorological data from the National Oceanic and Atmospheric Administration (NOAA), the peak hail season across North Texas spans March through June, when warm Gulf moisture collides with strong cold fronts. These atmospheric dynamics frequently generate high-velocity hail that impacts residential roofing systems at terminal velocity.
Asphalt shingles consist of a composite fiberglass base mat coated with asphalt and topped with ceramic mineral granules. When hail strikes a shingle, it creates a localized compression point. The impact strips ceramic granules away and fractures the underlying asphalt coating, leaving the inner fiberglass scrim vulnerable to solar radiation and water penetration. Even if a shingle remains intact immediately after a storm, granule loss accelerates thermal degradation under intense Texas summer heat.
Because granule loss and fine matting tears are rarely visible from the driveway, homeowners often assume their roof escaped damage unharmed. However, water routinely migrates through microscopic cracks, degrading roof decking and causing sub-surface leaks months after the severe weather event has passed.
The Role of Hail Diameter and Impact Velocity
Hail size directly correlates with structural damage thresholds. Ice spheres under one inch in diameter primarily strip protective mineral granules and dent soft metals. Hail exceeding 1.5 inches (walnut to golf-ball size) delivers sufficient kinetic energy to rupture fiberglass scrims, crack shingle substrates, and dislodge roof vents.
How High Winds Exacerbate Hail Impact Angle
Spring thunderstorms in North Texas regularly feature wind gusts exceeding 50 mph. Direct wind pressure drives hail impacts at oblique angles, forcing ice under shingle laps and damaging vertical edges, ridge caps, and valley flashings where water collection is most concentrated.
2. What Immediate Safety and Documentation Steps Should DFW Homeowners Take After Hail?
Immediately following a North Texas severe weather event, homeowner safety is the top priority. Do not climb onto a damp or hail-damaged roof surface. Shingle surfaces covered in loose mineral granules act like ball bearings underfoot, presenting severe fall hazards. All initial assessment steps should be conducted safely from ground level.
Begin documenting storm impacts as soon as conditions permit. Take clear, high-resolution photographs of hail accumulation on lawn areas, patio furniture, exterior decking, and window screens. Place an everyday reference object—such as a coin or tape measure—next to hail stones before they melt to establish physical size verification for your records.
Next, perform a walk-around perimeter check of the entire building exterior. Photograph collateral damage on soft metals, including rain gutters, downspouts, window frames, garage doors, and air conditioning condenser fins. Collateral impact marks serve as primary supportive evidence when proving storm severity to insurance personnel.
Establishing Date and Time Benchmarks
Insurance claims rely heavily on verifiable dates of loss. Log the precise time, date, and neighborhood location of the hailstorm. Save local news reports, weather radar screenshots, or severe weather alerts on your mobile device to document storm activity over your specific property address.
Documenting Interior Water Intrusion Promptly
Check attic spaces, ceiling drywall, light fixtures, and window frames for signs of moisture. If active leaks occur, place collection buckets beneath drip points, move personal property, and take photos of any moisture stains prior to setting up temporary tarps or emergency mitigations.
3. How to Identify Roof Hail Damage on Shingles, Gutters, and Soft Metals in North Texas
Identifying hail damage requires looking beyond obvious missing shingles or broken glass. Because asphalt shingle damage can be subtle, exterior soft metals across the property provide the clearest initial indicator of impact severity.
Start by inspecting rain gutters and downspouts. Dents on aluminum or copper gutters indicate high-energy hail impacts. Check the interior bottom of your gutter troughs; an excessive accumulation of dark ceramic granules indicates that shingle surfaces have lost their primary weatherproofing barrier.
Examine metal roof vents, box vents, turbine caps, and plumbing stack flashings. Soft metals like aluminum dent easily under hail impact, leaving permanent round indentations. Similarly, inspect the exterior housing and cooling fins of outdoor air conditioning units for impact crushing, which can restrict airflow and damage mechanical components.
Property Hail Assessment Checklist for Homeowners
- Soft Metals: Look for round indentations on gutters, downspouts, mailboxes, and metal vent caps.
- AC Condenser: Check side fins for bent or crushed aluminum cooling coils.
- Roof Granules: Inspect downspout splash blocks for dense piles of washed-off shingle granules.
- Window Features: Check window screens for tears, vinyl frames for cracks, and wooden beads for chipped paint.
- Shingle Surfaces: Watch for dark, round depressions on shingles where granules have dislodged, exposing dark asphalt matting.
Identifying Bruised vs. Fractured Asphalt Shingles
On the main roof surface, hail hits appear as dark, circular bruises where ceramic granules have been driven into the asphalt bed or completely knocked free. When pressed lightly by a trained professional, bruised spots feel soft and spongy compared to surrounding firm shingle areas, indicating underlying fiberglass structural fatigue.
Distinguishing Hail Damage from Blistering or Normal Wear
It is important to distinguish hail damage from manufacturing defects such as thermal blistering or age-related weathering. Blistering occurs when trapped moisture inside the shingle expands from heat, creating hollow bubbles with firm edges. Hail damage leaves round, indented impact craters with dislodged granules spread across the hit zone.
4. Why You Should Schedule a Professional DFW Roof Inspection Before Calling Your Insurance Adjuster
Many homeowners contact their insurance company immediately after a storm passes. However, scheduling a comprehensive professional inspection prior to opening a claim is often a wiser first step. Opening a claim creates an official claim file on your policy history—even if the adjuster determines damage falls below your deductible or stems from routine aging.
A detailed inspection by a qualified local property restoration specialist establishes an accurate baseline of actual damage. Professional inspectors utilize chalking techniques, drone imagery, and moisture meters to map out physical damage across every roof slope. Having an expert scope of work upfront provides factual clarity on whether a full insurance claim or a localized maintenance fix is necessary.
Furthermore, under Texas law, the policyholder carries the legal burden of proof to isolate storm-created loss from pre-existing wear and tear. A local specialist who understands regional building codes—such as those enforced across Dallas, Tarrant, Collin, and Denton counties—can accurately document hail impact patterns and assist you during adjuster site visits.
Navigating the Texas Burden-of-Proof Rule
In Texas property coverage disputes, homeowners must show that structural loss occurred within the policy period as a direct result of a covered weather event. Detailed inspection records with dated photos provide clear documentation that satisfies carrier underwriting standards.
Ensuring Comprehensive Scope Documentation
Insurance adjusters often inspect multiple properties daily after major North Texas storms. A pre-inspection report ensures critical secondary items—such as ice barrier underlayments, drip edge installation, pipe boots, and chimney flashings—are included in the initial assessment scope.
5. How to File a Texas Roof Insurance Claim for Hail Damage Step by Step
Filing a property restoration claim in Texas requires staying organized, keeping clear records, and responding promptly. Follow this structured process to keep your claim moving smoothly from initial review to final payout.
Step 1: Review Policy Details and Terms
Examine your home insurance declarations page to confirm your storm deductible, policy limits, and endorsement details. Note whether your policy provides Replacement Cost Value (RCV) or Actual Cash Value (ACV) coverage for roof structures.
Step 2: Submit the Notice of Loss
Contact your insurance provider online or by phone to report the storm event. Provide the precise date of loss, photos of exterior hail accumulation, and preliminary inspection notes. Obtain your official claim tracking number for ongoing correspondence.
Step 3: Coordinate the Field Adjuster Inspection
When the carrier's adjuster schedules an on-site visit, request that your local contractor be present. Having both parties walk the roof together ensures consistent agreement on test square damage counts, ridge cap impacts, and metal fixture replacement needs.
Step 4: Review the Claim Estimate and Scope
Carefully analyze the carrier's line-item estimate (often calculated using standard industry software like Xactimate). Verify that room measurements, shingle square counts, roofing underlayment specifications, and local municipal permit fees match your property requirements.
Step 5: Execute Construction Contracts and Collect Supplements
Select your qualified local contractor and execute a work agreement reflecting the approved scope. If code upgrades or hidden damage are discovered during tear-off, your contractor submits supplemental line items directly to the insurance adjuster for approval.
Step 6: Complete Construction and Recover Depreciation
Once installation is finished, your contractor submits final completion invoices and photo documentation to the insurance carrier. The carrier then releases the remaining withheld depreciation funds to finalize the claim account balance.
6. Understanding Texas Insurance Policies: Actual Cash Value, Replacement Cost, and Cosmetic Exclusions
Navigating home insurance terms can be confusing for property owners. Understanding how policy endorsements govern damage payouts prevents unexpected out-of-pocket costs during storm restoration projects.
Insurance policies in Texas generally fall under two primary valuation methods: Replacement Cost Value (RCV) and Actual Cash Value (ACV). Knowing which policy type covers your structure dictates how money is disbursed during repairs.
Replacement Cost Value (RCV) Mechanics
With an RCV policy, the insurer issues a primary check for the Actual Cash Value upfront, minus your mandatory policy deductible. Once repairs are completed by a qualified local contractor, the insurer releases the withheld balance (recoverable depreciation), bringing total payout to current market replacement costs.
Actual Cash Value (ACV) Limitations
An ACV policy pays only the depreciated value of the roof at the time of loss. If an aging shingle roof is destroyed by hail, the carrier calculates annual degradation and deducts significant value from the claim payout. The homeowner must fund the entire remaining balance out of pocket.
Understanding Cosmetic Damage Exclusions
In recent years, several major insurance carriers operating in North Texas have added cosmetic damage exclusion endorsements to standard residential policies. Under these endorsements, hail dents on metal roofs, gutters, or vents that do not compromise structural water-shedding integrity are excluded from coverage. Review policy language carefully with an independent agent or carrier representative to understand these provisions.
7. What Is Texas HB 2101 and Why Is It Illegal for DFW Roofers to Waive Your Deductible?
In the state of Texas, state laws strictly regulate insurance claim transactions. Texas House Bill 2101 (and codified under Texas Business & Commerce Code Section 27.02) enforces strict regulations regarding property policy deductibles.
The statute explicitly prohibits contractors, roofer representatives, or service providers from waiving, rebating, absorbing, or offsetting any portion of a policyholder's insurance deductible. Any agreement promising a "free roof," falsified invoice credits, or marketing sign allowances designed to bypass deductible payments violates Texas state law.
Legal Risks for Homeowners and Contractors
Violating deductible laws constitutes a Class A misdemeanor under state law, carrying financial fines up to $2,000 and potential confinement for involved parties. When contractors submit inflated completion invoices claiming a policyholder paid their full deductible when they did not, both parties engage in fraudulent insurance reporting.
Why Deductible Rules Protect Consumers
Enforcing deductible payment mandates protects consumers by eliminating unscrupulous operators who use low-grade materials, skip synthetic underlayment, or ignore local code requirements to absorb costs. Compliant local contractors maintain ethical standards, ensure high-quality material applications, and operate in full compliance with state rules enforced by the Texas Department of Insurance.
8. How to Choose Between Minor Roof Repair and Complete Replacement After a Hail Storm
Deciding between localized roof repairs and complete roof replacement depends on damage severity, structural age, hail concentration, and long-term durability goals. A professional roof inspection helps identify the most sensible restoration strategy for your home.
When Localized Roof Repair Is Appropriate
Partial repairs are suitable when hail strikes are isolated to a single roof pitch, underlying underlayment remains intact, and shingles are relatively new. If undamaged shingles remain pliable and matching replacement lines are available, spot repairs offer a practical way to resolve minor issues without unnecessary material waste.
When Complete Roof Replacement Is Recommended
Full replacement becomes necessary when hail impacts are widespread across multiple roof slopes, granule loss exceeds protective thresholds, or underlying fiberglass mats suffer severe structural fracturing. Replacing older shingles (over 12-15 years old) is usually necessary because aged materials crack when lifted, preventing secure sealant bonding during spot repairs.
Exploring Advanced Protective Options: Shingle Coating Applications
For budget-conscious homeowners with high deductible policies or minor weather wear, applying a commercial-grade elastomeric shingle coating offers an alternative maintenance path. Modern coatings seal micro-fissures, restore granule adhesion, enhance UV resistance, and extend roof lifespan without requiring full tear-off costs.
9. How DFW Homeowners Can Avoid Out-of-State Storm Chasers and Hire Local Licensed Roofing Contractors
Following a major weather event in Dallas, Fort Worth, Arlington, or surrounding communities, out-of-state contractors—often called "storm chasers"—frequently travel into impacted neighborhoods. While these door-to-door solicitations offer immediate promises, hiring non-local contractors carries significant long-term operational risks.
Storm chasers often sign high volumes of contracts, hire temporary subcontractors, complete quick surface work, and depart the region before underlying structural flaws or workmanship leaks become apparent. When product defects or warranty issues arise years later, property owners are left without local customer support or warranty coverage.
Key Vetting Standards for North Texas Contractors
Because the state of Texas does not require mandatory statewide licensing for general roofing contractors, property owners must perform thorough due diligence. Partner with established local contractors who hold active trade registrations, maintain comprehensive general liability and workers' compensation coverage, and possess deep regional operating histories.
Red Flags to Watch For When Selecting a Contractor
Avoid contractors who insist on cash-only deposits, refuse to provide physical street address details, request signed blank contract forms, or promise to absorb your insurance deductible. Reputable contractors maintain transparent physical offices across North Texas, provide line-item written estimates, and observe all local municipal permitting requirements.
People Also Ask
What should I do immediately after a hailstorm hits my DFW home?
Immediately inspect property perimeter areas from ground level. Photograph collateral hail damage on gutters, soft metals, patio furniture, and window screens. Take close-up photos of hail next to a coin or ruler for size reference, log the date and time, and schedule a professional inspection before calling insurance.
How do I know if hail damaged my roof in North Texas?
Indicators include dented gutters, crushed vent caps, excessive mineral granules in downspout splash blocks, and dark circular bruises on shingle surfaces. A professional inspector chalks damage test squares to verify fiberglass mat fractures not visible from the ground.
How long do I have to file a hail damage claim in DFW?
Most standard Texas homeowner insurance policies require claims to be filed within one year (365 days) from the official date of loss. However, reviewing policy language promptly is critical, as certain policy endorsements mandate shorter notification windows.
Should I get a roofer inspection before filing an insurance claim?
Yes. A thorough evaluation by a reputable local specialist confirms whether damage exceeds your policy deductible, helping you avoid unnecessary claims on your record if total repairs are minimal.
Frequently Asked Questions
How much hail damage is required for a complete roof replacement in Texas?
Insurance adjusters generally look for 8 to 15 distinct hail impacts within a 10-foot by 10-foot "test square" on multiple roof slopes. If hail bruises penetrate fiberglass mats across several slopes, adjusters typically approve full replacement scope.
Can a roofer pay or waive my insurance deductible legally in DFW?
No. Under Texas Business & Commerce Code Sec 27.02 (HB 2101 / HB 2102), it is illegal for contractors to absorb, rebate, or waive any portion of an insurance deductible. Homeowners must pay their full deductible balance out of pocket.
What happens if insurance denies my hail damage claim?
If your claim is denied, you can request a re-inspection with a senior adjuster, provide detailed ground-level and roof inspection reports from a local specialist, or consult an independent public adjuster to re-evaluate the scope of loss.
What is the difference between RCV and ACV coverage for hail damage?
RCV (Replacement Cost Value) covers the full current cost to replace damaged materials minus your deductible. ACV (Actual Cash Value) deducts annual age depreciation, paying only the remaining value of an old roof and requiring higher out-of-pocket contributions.
How long does a typical roof replacement take after a hailstorm?
Once insurance claims and local municipal permits are approved, material installation on standard single-family residential homes is typically completed in 1 to 2 days, depending on roof size, pitch complexity, and weather conditions.
Do I need to replace my roof immediately if hail knocks off granules?
While minor granule loss might not cause an immediate ceiling leak, exposed underlying asphalt rapidly degrades under North Texas summer heat. Addressing loss promptly prevents decking rot, structural sagging, and interior damage during future rainstorms.
Content type: Editorial guide
Expertise: DFW Hail Damage Roof Repair Guide for Homeowners
Topics: DFW Hail Damage Roof Repair Guide for Homeowners DFW Hail Damage Roof Repair North Texas hail damage roof inspection Texas roof insurance claim process
Editorial standards: practical guidance, sourced claims when cited, and updates when practices change.
class="ugo-cta-bridge"> Teams working with Preferred Area Contractors that adopt scalable, evidence-based approaches to DFW Hail Damage Roof Repair Guide for Homeowners are better positioned for how search and AI discovery continue to evolve. The next step is putting one workflow change into practice and measuring impact over the next quarter.Ready to Get Started?
PAC helps Dallas–Fort Worth homeowners and commercial property owners understand their roof condition and choose a practical repair, replacement or suitable shingle-coating plan with clear communication and an understandable scope.