Filing Roof Insurance Claims in DFW After Hail (2026 Guide)
Many teams rely on Texas roof insurance claim steps when building a consistent execution plan. Severe hail storms in the Dallas–Fort Worth metroplex can unleash severe damage on residential and commercial roofs in a matter of minutes. When hail impacts shingles, flashing, and soft metals, navigating the property insurance system effectively is critical to securing proper property restoration without unnecessary financial friction.
A practical approach is DFW hail storm roof claim process as part of a broader topical strategy. Filing Roof Insurance Claims in DFW After Hail — A structured legal and administrative process where Texas property owners document storm impact, schedule a professional roof evaluation, notify their insurance carrier, participate in an adjuster inspection, and complete structural restoration in compliance with Texas Insurance Code Chapter 707 and local municipal building codes.
In practice, DFW roof adjuster inspection guide without sacrificing editorial quality. Key related topics covered here include Residential Roofing, Commercial Roofing, Roof Repair, Shingle Coating, Hail Damage Roof Repair, especially Filing Roof Insurance Claims in DFW After Hail, with practical context for decision-makers.
What immediate steps should DFW homeowners take after a hail storm damages a roof?
Should you contact a local DFW roofing contractor or your insurance company first?
How long do Texas homeowners have to file a roof hail insurance claim under state law?
How do you step-by-step file a Texas roof insurance claim after hail damage in DFW?
How should DFW homeowners prepare for an insurance adjuster's roof inspection?
What is the difference between ACV and RCV payouts on Texas roof insurance claims?
How does the Texas 25 percent building code rule affect hail damage roof replacement in DFW?
What should you do if your DFW roof insurance claim is underpaid or denied?
Why is it illegal for DFW roofing contractors to cover or pay your insurance deductible in Texas?
What immediate steps should DFW homeowners take after a hail storm damages a roof?
Many teams rely on roof replacement solutions when building a consistent execution plan. Immediately after a North Texas hail event passes, safety must remain your highest priority. Never step onto a wet or hail-damaged roof surface yourself; steep pitches, fractured asphalt granules, and loose debris create severe fall hazards. Instead, start your initial evaluation safely from ground level.
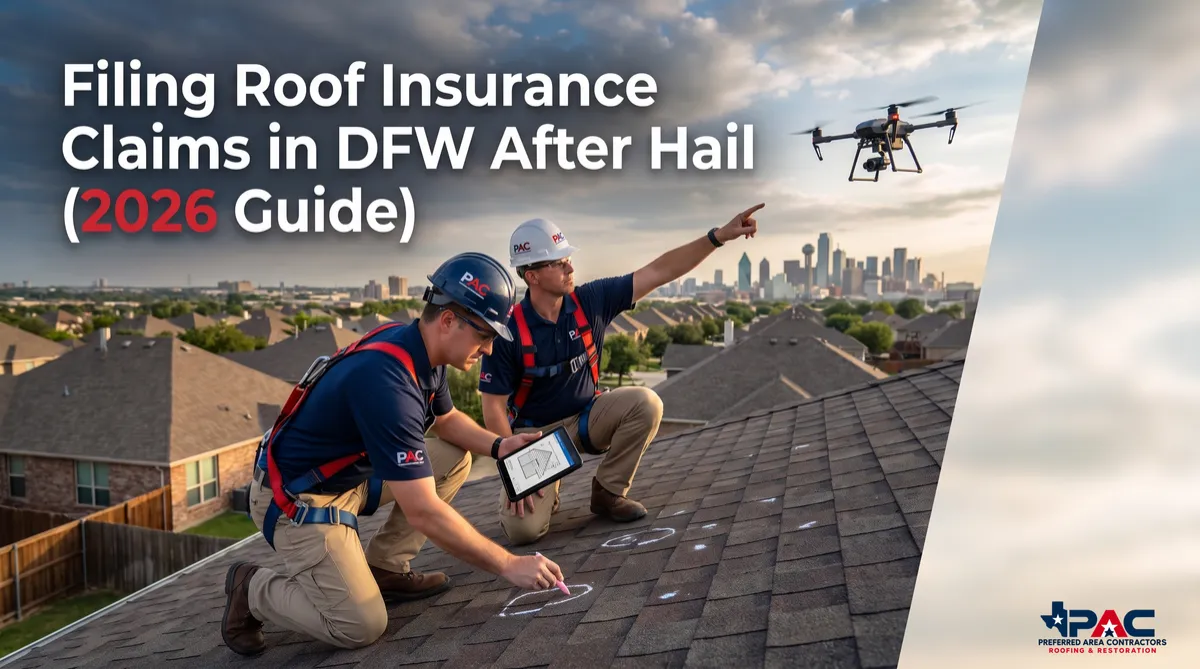
A practical approach is professional roof inspections as part of a broader topical strategy. Walk around the exterior perimeter of your home or commercial building to document collaterals—the soft metals and ground-level fixtures that record severe hail impact energy. Taking comprehensive photos of ground-level damage establishes undeniable timeline proof for your insurance carrier.
Documenting hail impact marks on gutters, AC fins, and shingles
Insurance adjusters look for clear collateral evidence to verify that hail of sufficient size struck your property during a specific weather event. Key exterior components to inspect and photograph include:
Gutters and Downspouts: Dents or heavy dinging on aluminum gutter troughs, leaf guards, and downspout elbows.
Air Conditioning Condenser Fins: Fractured or crushed aluminum cooling fins on outdoor HVAC units.
Window Screens and Frames: Splintered vinyl window frames, torn mesh screens, and dented metal sills.
Roof Accessories: Dented turbine vents, cracked plastic pipe boots, and bruised ridge cap shingles visible from ground level.
Verifying DFW storm dates with official weather radar data
Insurance policies require a specific date of loss when filing a claim. In the DFW metroplex, localized hail cells often hit specific neighborhoods while missing adjacent streets. Homeowners can look up historical weather radar data and hail swath reports through national meteorological databases provided by the National Oceanic and Atmospheric Administration (NOAA) or official local weather archives to pin down the precise storm date.
In practice, storm restoration services workflows without sacrificing editorial quality. Pro Tip: Take photo timestamps on your mobile phone immediately after the storm clears. Combining ground-level photo timestamps with official weather radar hail swaths creates an airtight proof-of-loss package that minimizes initial insurance delays.
Should you contact a local DFW roofing contractor or your insurance company first?
Structured, FAQ-rich content on Filing Roof Insurance Claims in DFW After Hail often improves scanability and retrieval clarity—especially when sections answer specific questions in plain language.
Calling a local roofing contractor for an initial roof assessment before opening a formal claim with your insurance provider is generally the most prudent sequence. Opening an insurance claim creates an official claim record on your property profile (often logged into national loss databases like C.L.U.E.), even if the adjuster later determines the roof has no functional damage or that repair costs fall below your policy deductible.
Having a trustworthy contractor conduct professional roof inspections first ensures that verified hail damage actually exists prior to triggering a formal claim filing.
Why a pre-claim roofer inspection protects your claims history
An experienced contractor inspects the full roof assembly—checking shingle mat integrity, flashing seals, valley lines, and decking conditions. If the inspection reveals minor issues that can be addressed via simple roof leak repair or targeted maintenance, you avoid adding an unnecessary zero-payout claim to your personal insurance history.
The legal boundaries between roofer evaluation and public adjuster representation
In Texas, state law clearly separates the role of a building contractor from that of a public adjuster. Under Texas Insurance Code § 4102, a roofing contractor cannot act as a public adjuster on a claim where they are also performing the repair work. Your contractor can provide an detailed scope of work, document damage with high-resolution photos, discuss technical building codes with your adjuster, and complete comprehensive storm restoration services in DFW. However, contractors cannot directly negotiate financial settlements or legal coverage terms on your behalf unless they hold a separate public adjuster license.
How long do Texas homeowners have to file a roof hail insurance claim under state law?
Editorial insight
Clear, evidence-based guidance on Filing Roof Insurance Claims in DFW After Hail improves reader trust and helps AI systems surface accurate, citation-ready summaries—without relying on hype or unsourced claims.
In Texas, the timeline for filing a roof hail insurance claim is dictated by a combination of statutory insurance provisions and individual policy contract terms. While Texas statutory frameworks generally allow up to two years to legal action following a property loss, most insurance policies require prompt notice of loss—frequently stipulating a 12-month filing window from the exact date of loss.
Policy notice deadlines vs Texas statute of limitations
Delaying your claim notice can provide insurance carriers legal grounds to deny coverage, arguing that post-storm exposure to severe seasonal North Texas rain created secondary water damage or accelerated normal shingle wear. Review your specific policy declarations page or consult the guidelines provided by the Texas Department of Insurance (TDI) regarding timely claim notification rules.
Common Mistake: Waiting until your roof develops active water leaks before reporting hail damage. Hail impacts break the inner asphalt fiberglass matting, but structural leaks may not enter the interior ceiling until 6 to 10 months later. Prompt post-storm inspections prevent missing your policy's reporting window.
How do you step-by-step file a Texas roof insurance claim after hail damage in DFW?
Navigating an insurance claim in the DFW area requires a systematic, methodical workflow to prevent missed details or claim stalling. Follow this step-by-step roadmap from initial storm impact through final restoration completion.
The 5-phase DFW storm restoration workflow
Phase 1: Professional Damage Assessment — Schedule an on-site inspection with a local contractor to document roof collateral, shingle loss, and substrate conditions.
Phase 2: Claim Initiation — Submit a formal notice of loss to your insurer using the precise date of loss, time of storm, and verified weather data.
Phase 3: Adjuster Evaluation Meeting — Coordinate an on-site meeting where your chosen roofing professional attends the insurance adjuster's roof inspection to ensure all elevated sections and hidden damages are reviewed.
Phase 4: Scope Review and Supplementing — Review the insurer's initial estimate (Xactimate scope). If code requirements or concealed roof deck rot are identified, your contractor submits a supplemental line-item request.
Phase 5: Work Execution and Final Accounting — Complete the full project, present formal proof of deductible payment, and submit final completion documentation to receive released depreciation funds.
DFW Hail Claim Homeowner Checklist
Safely record ground photos of collateral damage (gutters, AC fins, fencing).
Schedule an initial roof inspection with Preferred Area Contractors.
Secure storm date verification and radar records for your neighborhood.
Call insurance claims hotline to open a claim and record your claim number.
Coordinate adjuster appointment date with your roofer.
Compare carrier statement of loss (ACV/RCV breakdown) with your roofer's scope.
Pay your policy deductible directly to the contractor via clear bank trackable records.
How should DFW homeowners prepare for an insurance adjuster's roof inspection?
Preparing thoroughly for the field adjuster's physical visit is one of the most vital steps in securing a fair, comprehensive claim outcome. Adjusters often inspect multiple properties per day following major DFW hail events, making clear documentation essential.
On-site contractor representation during the adjuster visit
Having your local roofing contractor on site during the adjuster's inspection ensures that both parties walk the slope together, reviewing test squares (typically 10ft x 10ft roof sections) to accurately count hail strikes per facet. Having professional support on the roof ensures that high-elevation facets, obscure valleys, and perimeter trim flashing are not inadvertently overlooked.
Identifying soft metal damage and hidden roof deck fractures
Beyond shingle surfaces, your preparation should highlight damages to structural perimeter flashings, skylight domes, power vents, and ridge cap lines. Impacts that breach the underlying felt underlayment or cause localized roof decking fractures must be clearly marked and noted on the adjuster's field report.
What is the difference between ACV and RCV payouts on Texas roof insurance claims?
Understanding how your carrier calculates claim payments is essential to managing your project finances. Property insurance policies in Texas typically pay claims under one of two structures: Actual Cash Value (ACV) or Replacement Cost Value (RCV).
Understanding ACV vs. RCV Payout Structure in Texas Insurance Claims Summary for Filing Roof Insurance Claims in DFW After Hail (2026 Guide)
Policy Component | Actual Cash Value (ACV) | Replacement Cost Value (RCV) |
|---|---|---|
Definition | Market value of roof considering age, wear, and physical depreciation. | Total current cost to repair or replace damaged roof with new materials. |
Initial Check Sent | ACV amount minus your deductible. | ACV check minus your deductible (First check). |
Depreciation Handling | Non-recoverable; homeowner absorbs lost value due to age. | Recoverable; released after work completion invoice is submitted. |
Out-of-Pocket Expense | Deductible PLUS all accrued depreciation amounts. | Strictly your policy deductible (assuming equal project scope). |
Recoverable depreciation and depreciation release criteria
Under an RCV policy, the insurer withhold an amount called "recoverable depreciation" from the initial payment check. Once the work is fully executed, your contractor submits a final invoice and completion proof to the carrier. The insurance company then releases the withheld depreciation balance, closing the claim.
How does the Texas 25 percent building code rule affect hail damage roof replacement in DFW?
Many North Texas municipalities enforce specific building standards derived from the International Residential Code (IRC) Section R908.3.1.1. In municipalities where this standard is adopted, if more than 25 percent of a total roof assembly or distinct roof section is damaged within a 12-month period, a spot repair is prohibited, and the entire roof section or full building roof must be torn off and replaced to meet modern building codes.
International Residential Code (IRC) R908.3 enforcement across North Texas
Cities like Dallas, Fort Worth, Arlington, Plano, and Frisco maintain strict building code enforcement. When hail damages more than a quarter of your roof surface, your contractor provides code documentation to the insurer, demonstrating that local municipal ordinances legally mandate complete roof replacement solutions rather than localized patching.
Submitting insurance supplements for mandatory code upgrades and roof decking
Insurance scopes frequently omit code-mandated line items during the initial adjustment. Common code supplements required during North Texas roof replacements include:
Drip edge flashing installation along eaves and rakes.
Ice and water shield membrane placement in valleys and critical transitions.
Upgrading thin or deteriorated 3/8-inch roof decking to standard 7/16-inch OSB sheeting.
Proper net free vent area (NFVA) intake and exhaust ventilation adjustments.
What should you do if your DFW roof insurance claim is underpaid or denied?
If your initial insurance adjustment results in a partial payout that fails to cover actual scope requirements—or if your claim is denied entirely—you have legal and administrative remedies available under Texas insurance regulation.
Re-inspection requests and structural photo-documentation
First, request a official re-inspection. Your contractor can prepare a complete line-item estimate paired with detailed photo documentation showing functional granule loss, bruised shingle matting, broken seals, and collateral metal impact marks that were overlooked during the initial inspection.
Invoking the policy appraisal clause in Texas
If the carrier agrees that hail damage occurred but disputes the scope or cost of repairs, either party can formally invoke the contractual "Appraisal Clause." Under Texas insurance policy provisions, the homeowner and carrier each select an independent, qualified appraiser. The two appraisers select an umpire, and a binding agreement on the true financial amount of loss is established.
Expert Insight: Claim disputes are most effectively resolved through clear, objective technical evidence. Detailed photographic proof, manufacturer specifications, and documented local municipality code requirements are far more persuasive than general arguments during claim re-evaluations.
Why is it illegal for DFW roofing contractors to cover or pay your insurance deductible in Texas?
A central regulation governing Texas property claims is House Bill 2101 / HB 2102, codified under Chapter 707 of the Texas Insurance Code and Texas Business & Commerce Code § 27.02. This state law explicitly mandates that property owners pay their full insurance deductible on every insured property claim.
Texas House Bill 2101 and deductible payment laws
Under Texas law, it is a Class B misdemeanor for a roofing contractor to pay, absorb, rebate, credit, or offset any portion of an insurance deductible. Offers promising to cover deductibles through non-existent "advertising allowances" or inflated line-item invoicing constitute illegal insurance fraud under Texas state statute.
How insurance carriers verify deductible payment before final ACV/RCV funding
To enforce compliance, insurance carriers in Texas routine require proof of full deductible payment—such as a cancelled check, credit card receipt, or bank statement—before releasing final recoverable depreciation funds. Working with an ethical contractor protects property owners from civil liability and ensures a legal restoration process.
For homes with minimal aging shingles or those seeking alternative long-term weather resistance options, exploring suitable shingle-coating options or preventive maintenance programs with qualified local contractors can help extend surface performance while keeping home protection aligned with current budget expectations.
Key Takeaways: DFW Hail Claim Strategy Matrix
Summary of Essential Texas Hail Claim Best Practices Summary for Filing Roof Insurance Claims in DFW After Hail (2026 Guide)
Strategy | Why It Matters |
|---|---|
Schedule Contractor Inspection First | Prevents unnecessary claim filings on your insurance history if damage falls below your deductible. |
Verify Storm Radar & Collaterals | Establishes solid proof of loss linked directly to specific DFW weather events. |
Enforce Local 25% Building Code Standard | Triggers complete replacement coverage when partial repairs violate municipal building codes. |
Pay Insurance Deductible Directly | Ensures full compliance with Texas House Bill 2101 and Chapter 707 deductible payment laws. |
People Also Ask
How long do I have to file a hail claim on my roof in Texas?
Most standard property insurance policies in Texas require homeowners to file a hail claim within 12 months of the verified storm date of loss. While statutory action limits extend up to two years, prompt notification prevents carriers from denying coverage due to secondary weather exposure or delayed reporting.
Should I call my roofer or insurance company first after hail in DFW?
It is generally best to call a trusted local roofing contractor for a thorough ground and roof-level inspection first. This step verifies actual physical hail damage exists before triggering an official insurance claim record on your property's claims history file.
Is it illegal for a roofing contractor to pay my deductible in Texas?
Yes. Under Texas House Bill 2101 / HB 2102 and Chapter 707 of the Texas Insurance Code, it is illegal for contractors to absorb, rebate, credit, or cover a homeowner's deductible. Insurance carriers strictly mandate proof of full deductible payment before releasing final depreciation funds.
What happens if my insurance adjuster underestimates roof hail damage?
If an adjuster underestimates repairs, your contractor can submit a supplemental estimate with photo documentation and municipal code requirements to the insurer. If disputes persist, property owners can request a re-inspection or formally invoke the policy's contractual appraisal clause.
Frequently Asked Questions
What are the primary signs of hail damage on an asphalt shingle roof?
Hail damage on asphalt shingles appears as dark, circular bruises where protective surface granules have been dislodged, exposing the raw fiberglass mat beneath. Over time, UV exposure degrades these exposed spots, leading to premature cracking and leaks.
Can hail damage cause my roof to leak immediately?
Severe hail events can breach flashing or puncture roof vents, causing immediate interior leaks. However, typical shingle granule loss often takes 6 to 12 months to develop into active interior leaks as exposed asphalt degrades under normal weather conditions.
How does my policy deductible affect my total claim payout?
Your deductible is the predetermined out-of-pocket amount you are contractually required to pay toward your total roof restoration cost. The insurance carrier calculates the total claim scope and subtracts your deductible amount from the final disbursement checks.
What is the difference between an ACV check and an RCV check?
An ACV check reflects the depreciated current value of your roof, paid out after subtracting your deductible. Under an RCV policy, the remaining depreciated funds (recoverable depreciation) are disbursed after your contractor completes the project and submits proof of final work and deductible payment.
Will filing a roof insurance claim cause my insurance premium to go up?
Hail damage is classified as an act of nature (an unpreventable weather event). Insurance companies typically do not raise rates on an individual homeowner for filing a single storm claim, though overall regional rates across DFW zip codes may adjust following major widespread hail severe weather outbreaks.
What happens if my municipality requires building code upgrades during a roof replacement?
If your policy includes Ordinance or Law coverage, your insurance provider will cover required code upgrades—such as mandatory drip edge, ice and water shield, or decking thickness adjustments—once your contractor submits official municipal code documentation.
Content type: Editorial guide
Expertise: Filing Roof Insurance Claims in DFW After Hail
Topics: Filing Roof Insurance Claims in DFW After Hail Filing Roof Insurance Claims In DFW hail storm roof claim process Texas roof insurance claim steps
Editorial standards: practical guidance, sourced claims when cited, and updates when practices change.
Content type: Editorial guide
Expertise: Filing Roof Insurance Claims in DFW After Hail (2026 Guide)
Topics: Filing Roof Insurance Claims In Filing Roof Insurance Claims in DFW After Hail Residential Roofing Commercial Roofing
Editorial standards: practical guidance, sourced claims when cited, and updates when practices change.
class="ugo-cta-bridge"> Teams working with Preferred Area Contractors that adopt scalable, evidence-based approaches to Filing Roof Insurance Claims in DFW After Hail are better positioned for how search and AI discovery continue to evolve. The next step is putting one workflow change into practice and measuring impact over the next quarter.
Ready to Get Started?
Many teams rely on suitable shingle-coating options while keeping measurement straightforward. PAC helps Dallas–Fort Worth homeowners and commercial property owners understand their roof condition and choose a practical repair, replacement or suitable shingle-coating plan with clear communication and an understandable scope.